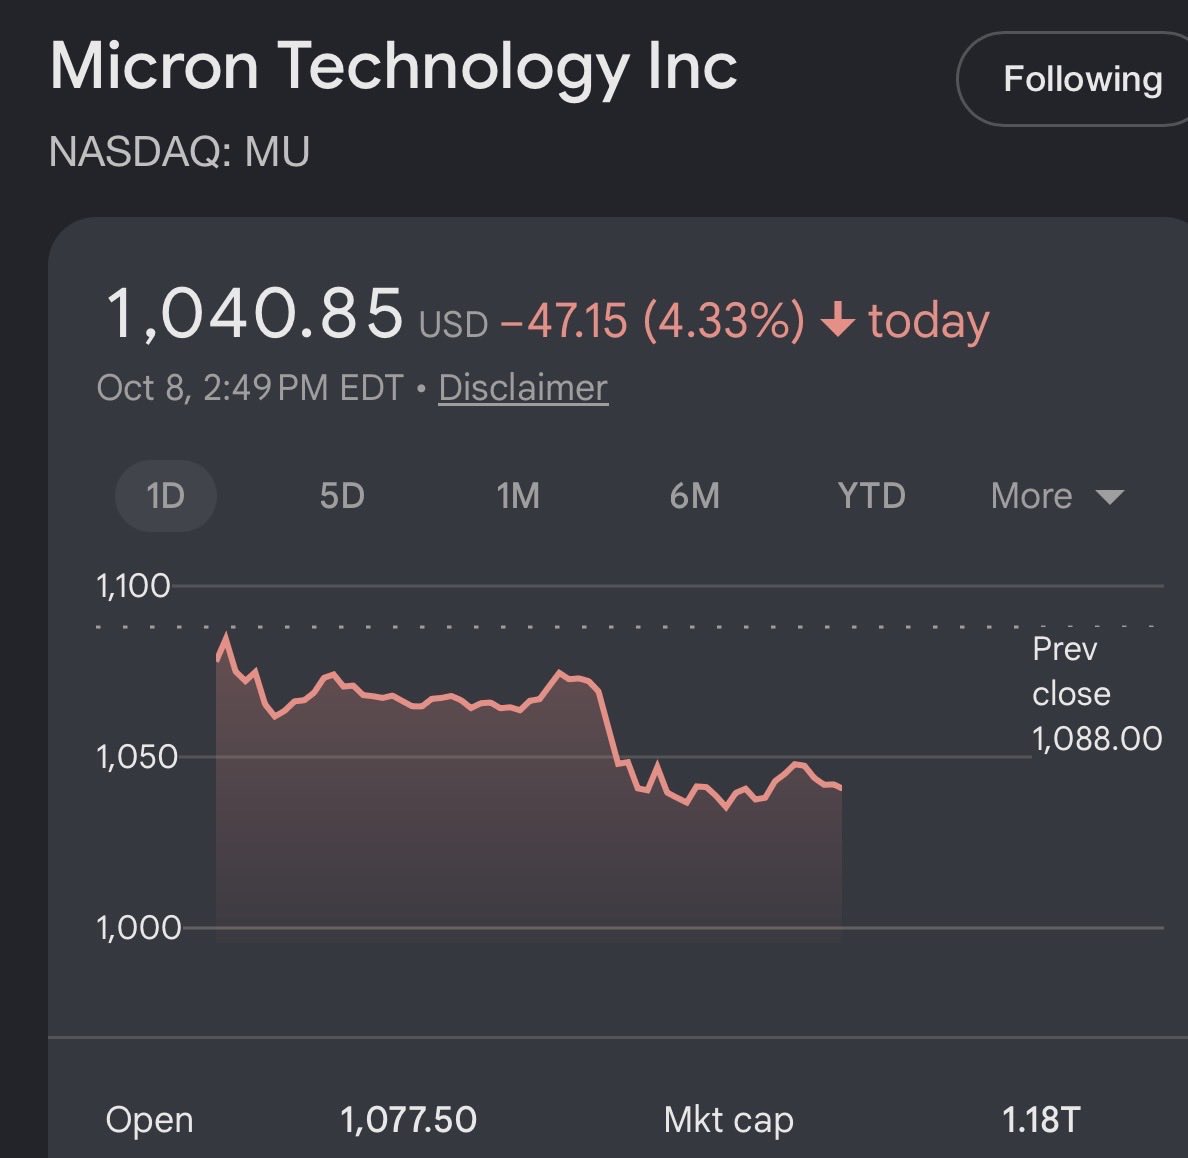
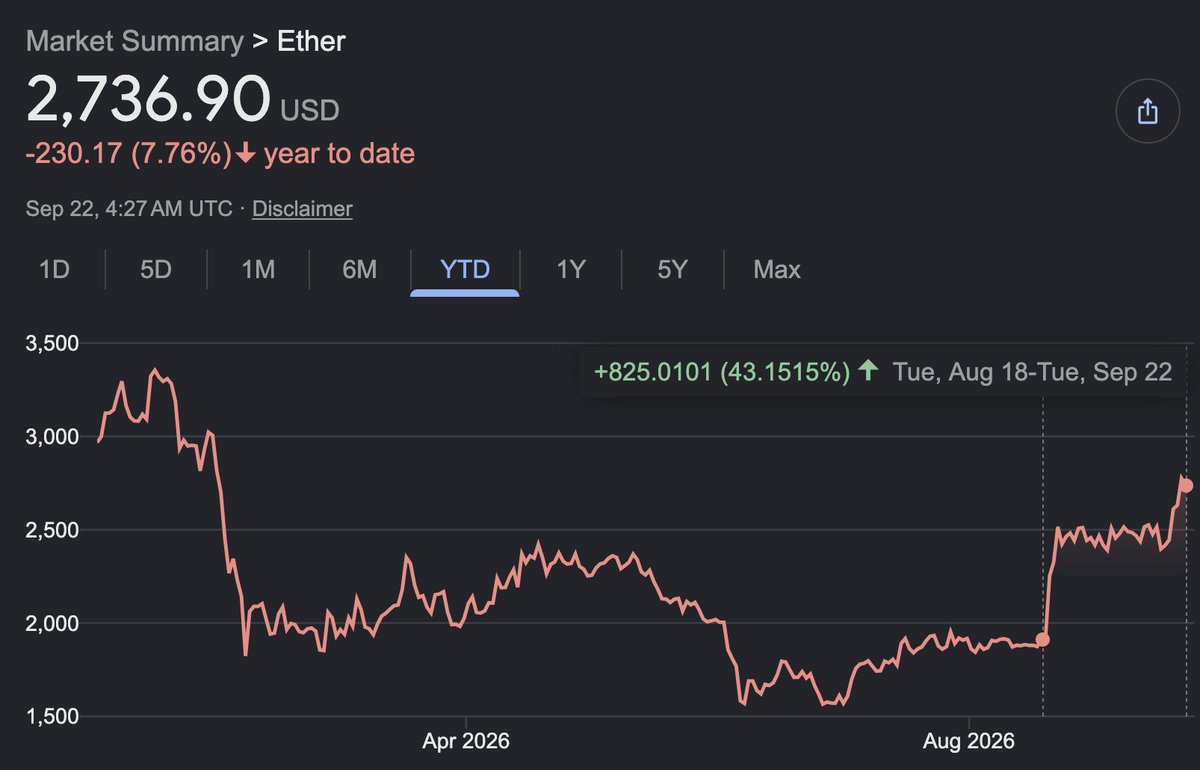
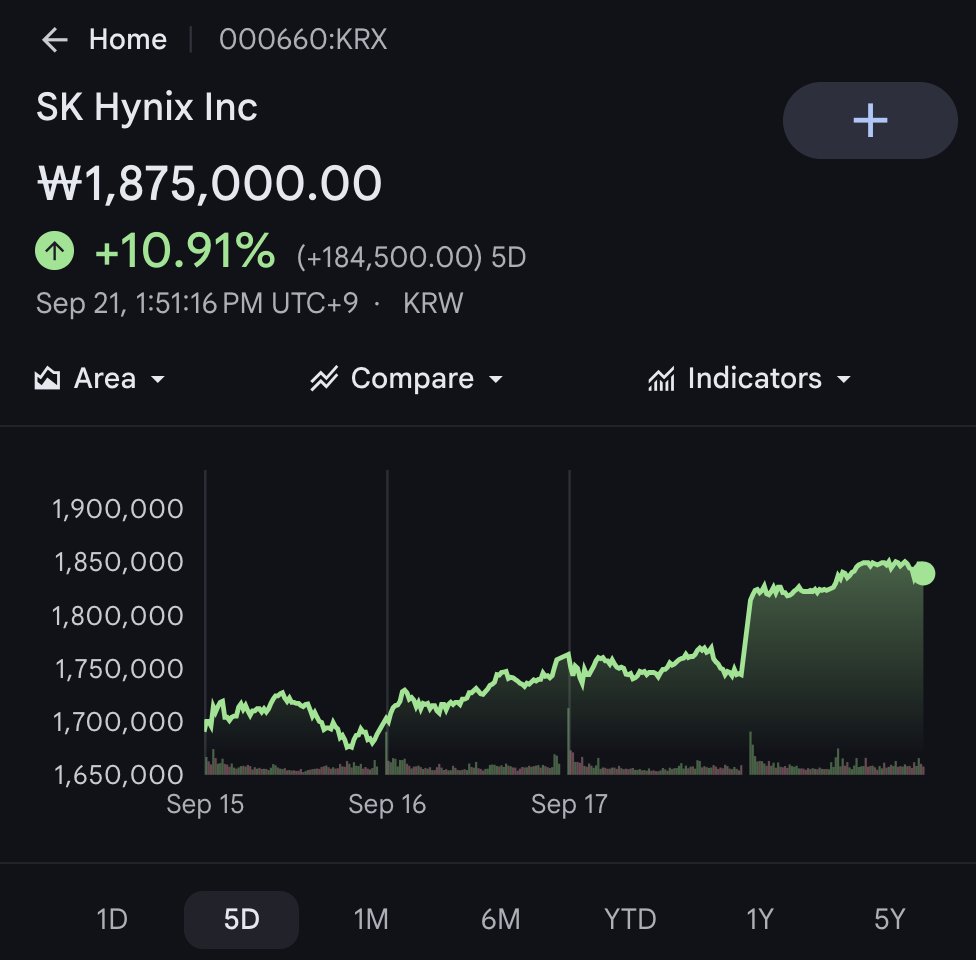
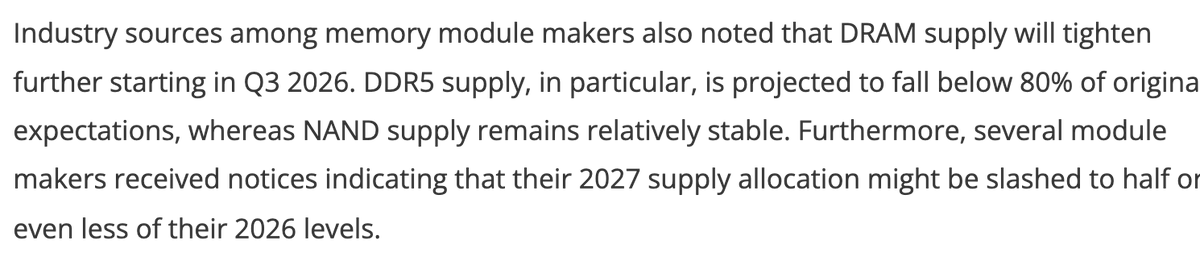
中文那么关于光学与光子学……像$MU / $SKHY这样的存储正处于当前的超级周期中。
-> 例如,RBC渠道调研预计2027年HBM ASP涨幅达80-100%。
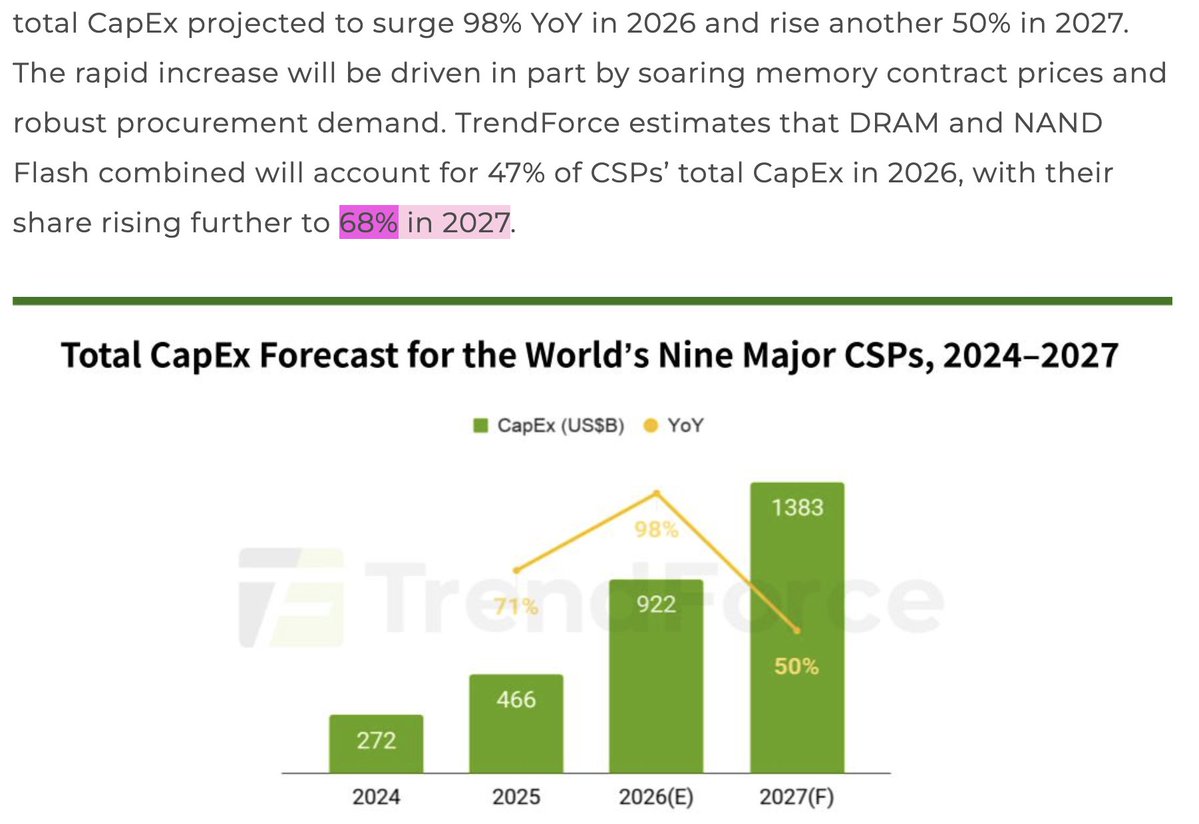
-> 根据$NVDA财报,超大规模厂商资本开支在2027年上升。然后根据Trendforce,超大规模厂商资本开支的68%流向DRAM/NAND。
-> 未来3-5年已有50-70%分配给长期协议(LTA)。
所以超级周期已经到来……需求可见性很高,价格涨幅仍在持续。
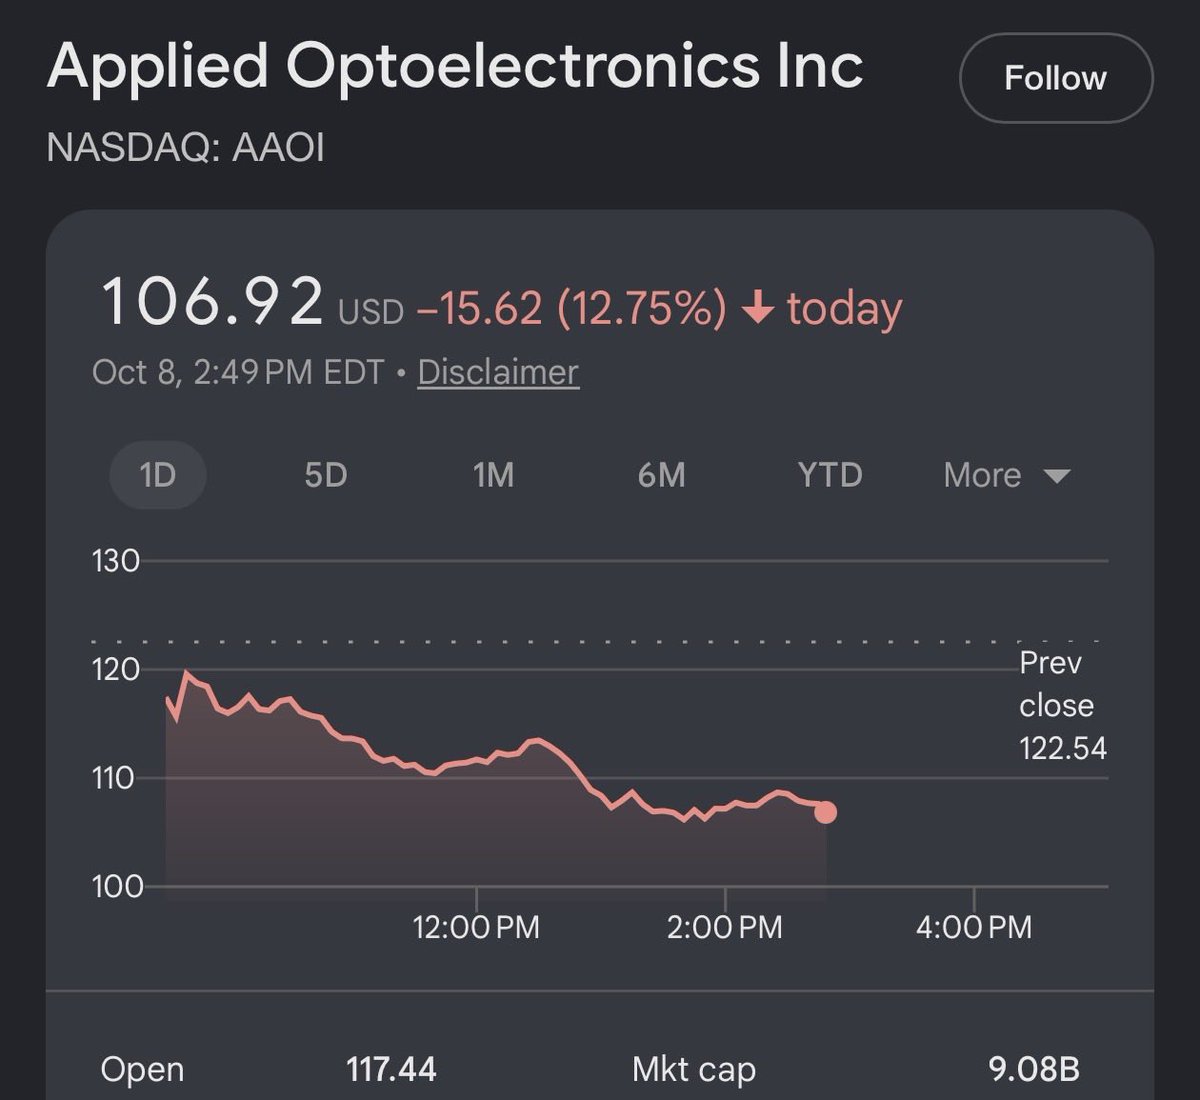
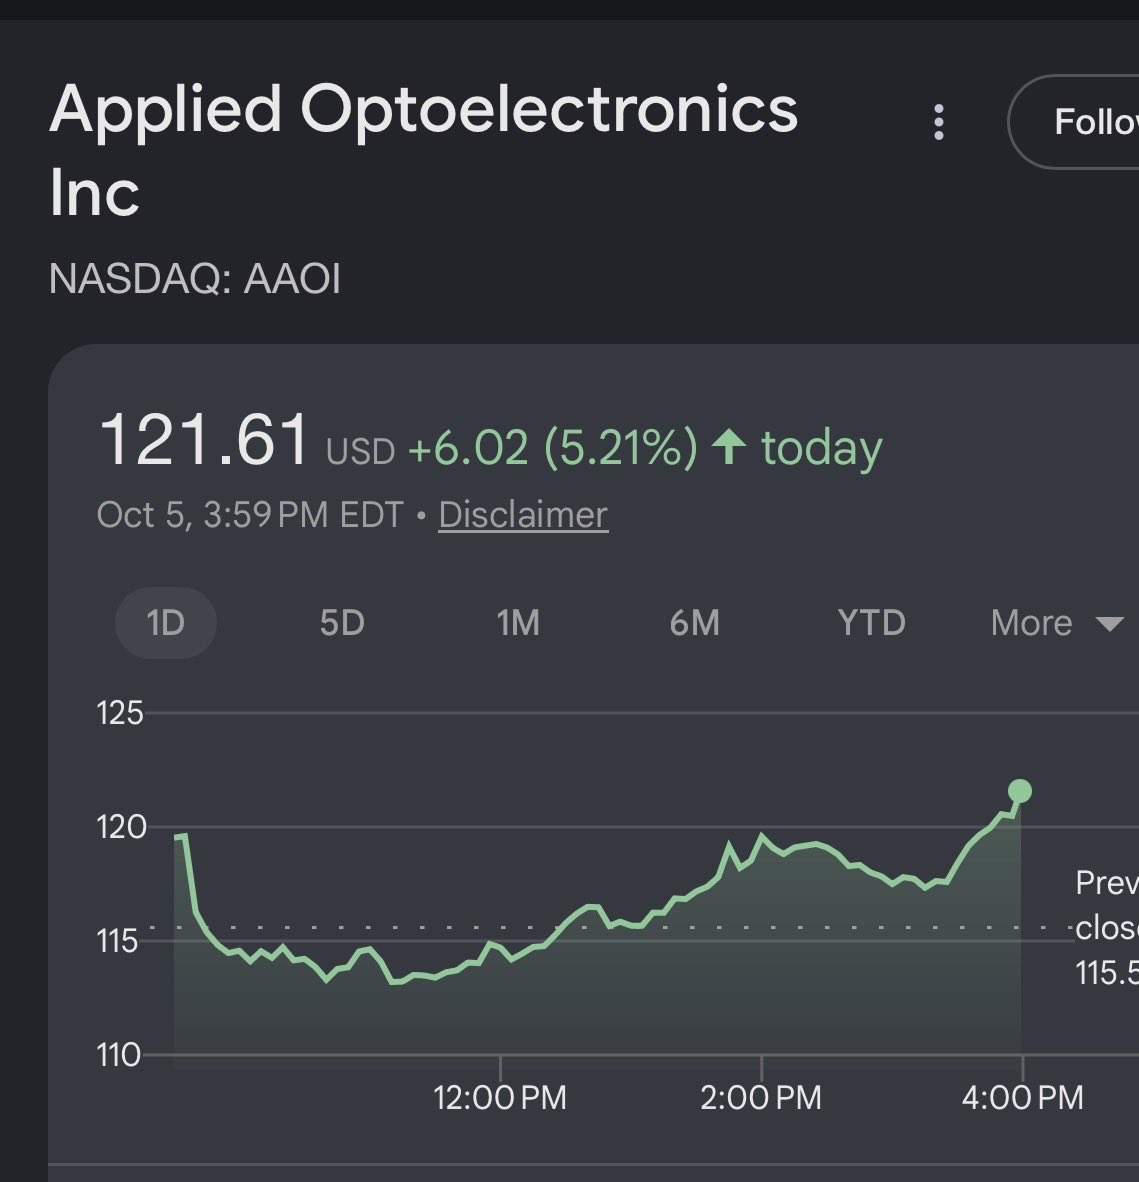
至于像$SMTC到$AAOI这样的光子学股票,我预计2027年会大幅升温,因为我们在2026年已经看到广泛的光学短缺。
此外,光模块的TAM将从2026年的677亿美元(据GS)增至2027年的1314亿美元……
这在CPO于2028年真正开始规模化之前,影响DSP/TIA/激光器/光纤供应商。
我不认为我们会看到同样规模的存储价格涨幅,但我确实认为光学供应链中的MC增长还有很大空间(考虑到起点较小,例如10亿美元的CW激光器供应商对比1万亿美元的存储制造商)。
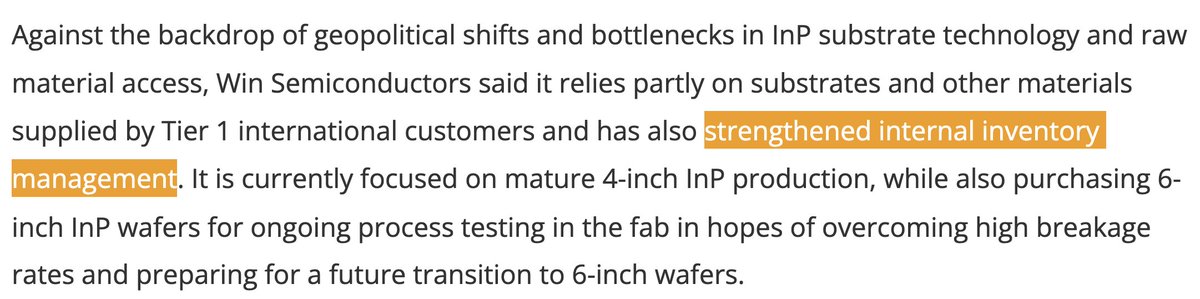
但仍然有激光器含量价格上涨的空间(例如,据GS报告,4个70 mW激光器15-20美元),因为起点非常便宜……而一个组件,比如廉价的InP衬底,可能破坏下游价值数千亿美元的供应链。
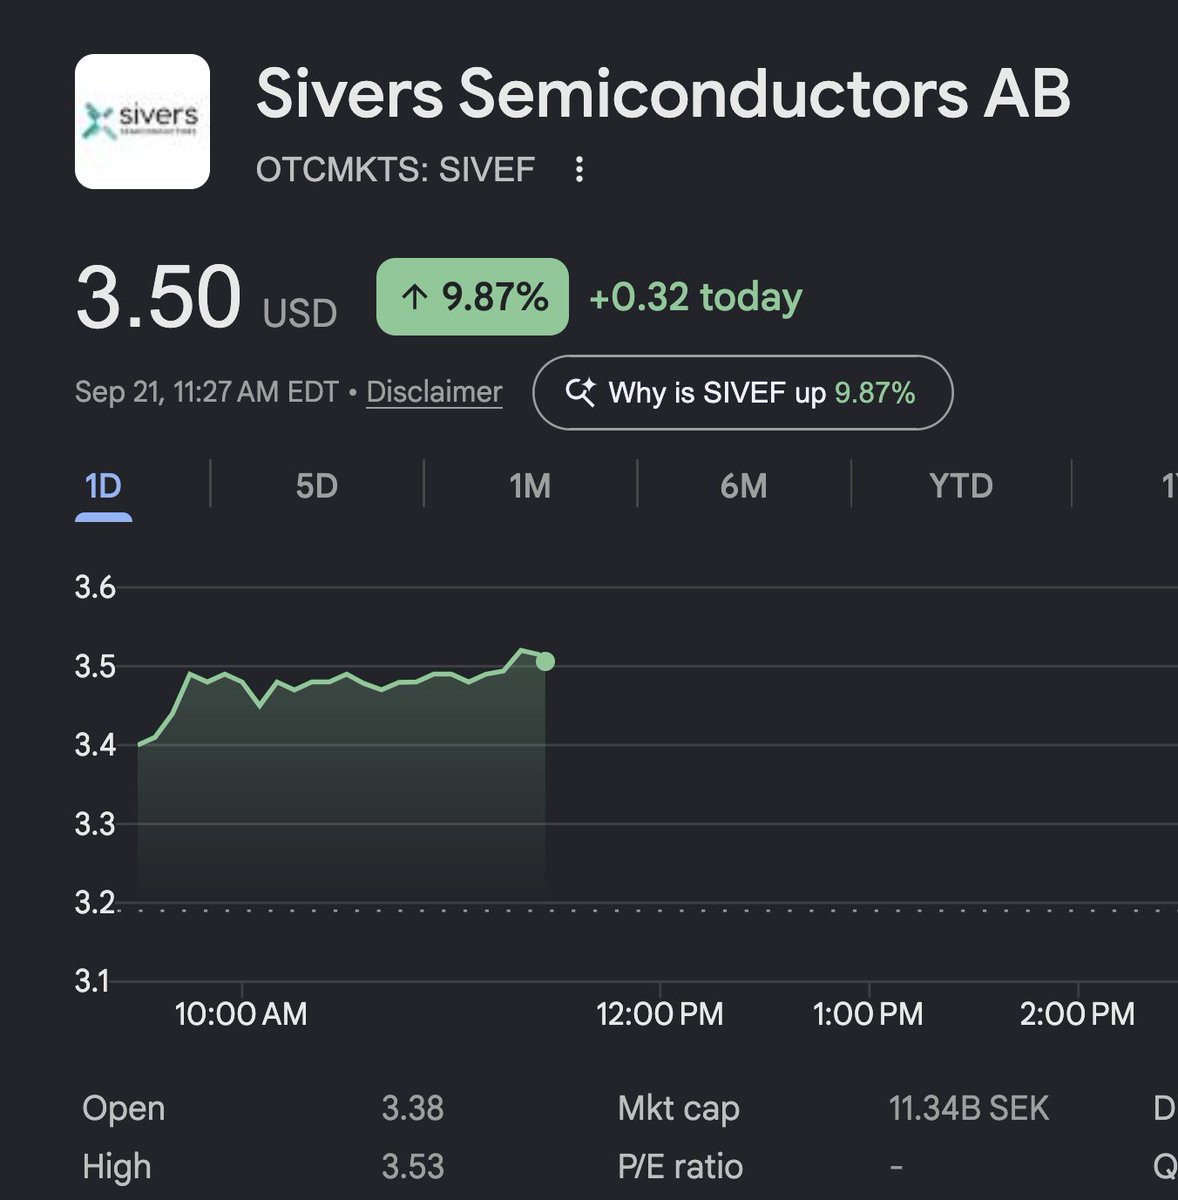
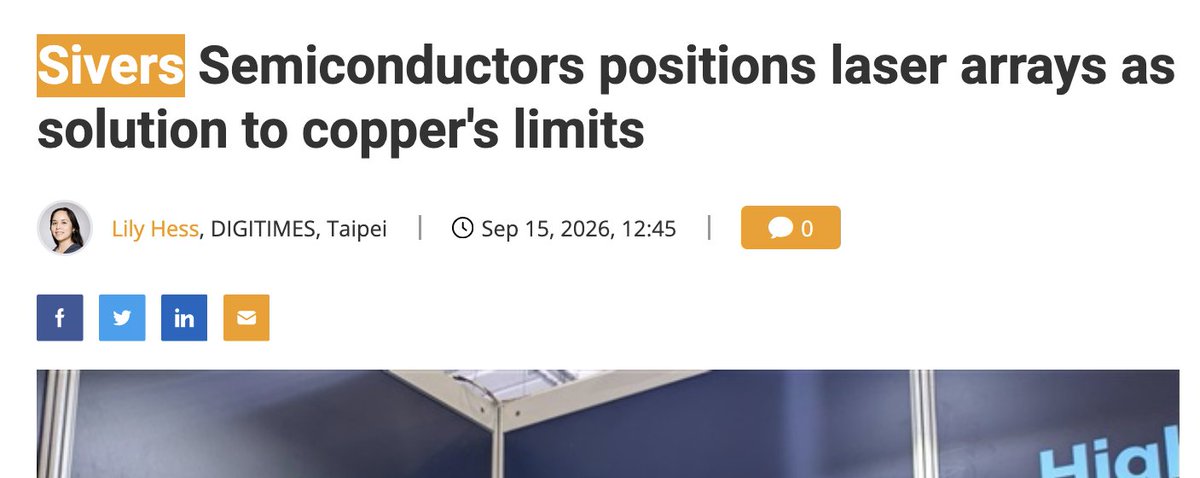
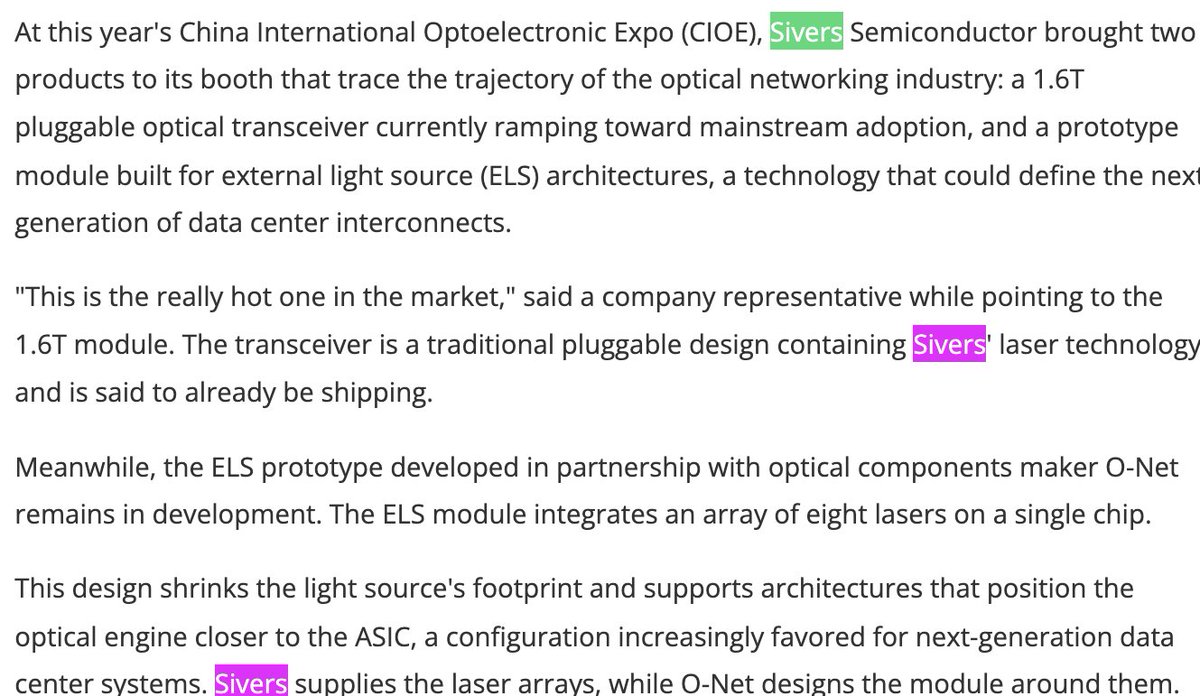
不过,我们已经从CIOE渠道调研中看到激光器价格上涨,这得到了Innolight和$SIVE以及Serenity的粉丝渠道调研的证实。
因此进入未知领域。
简而言之:思路有些乱,但存储在近期具有盈利动能,正处于当前超级周期之中。
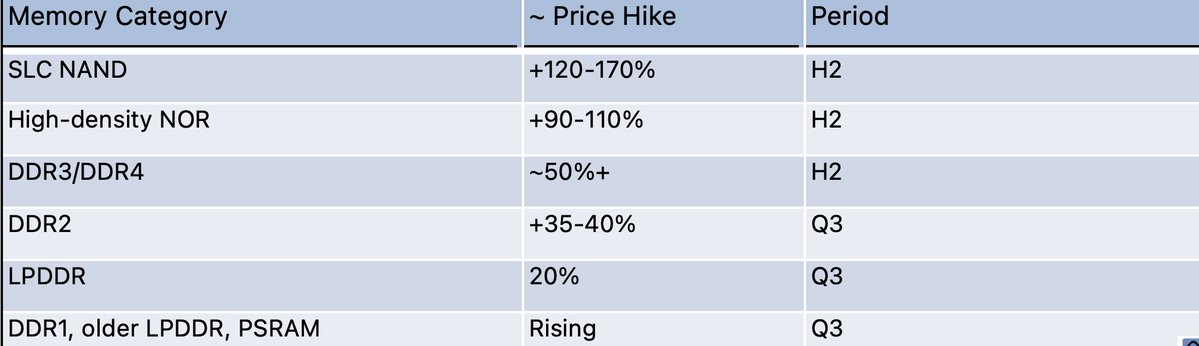
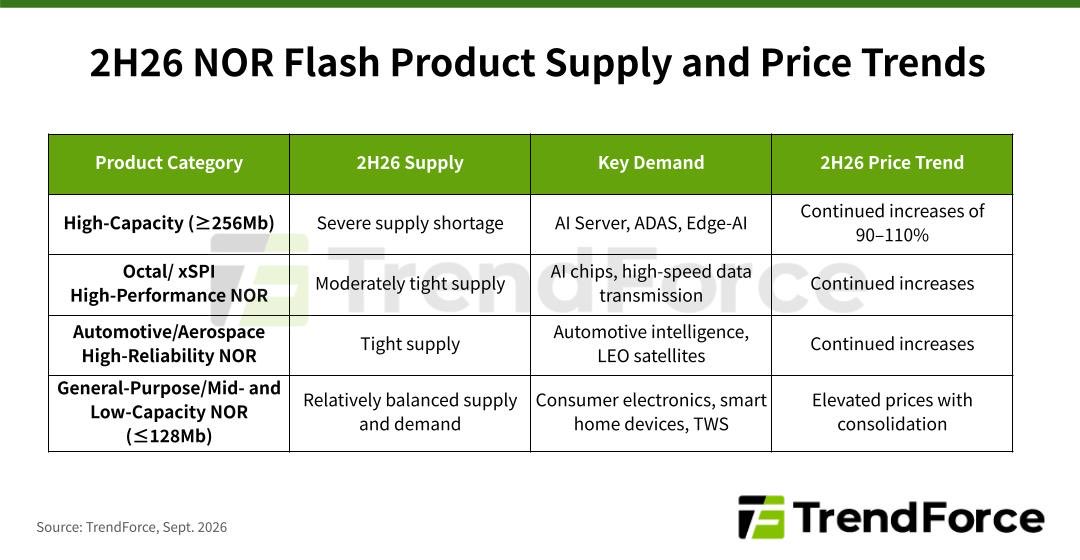
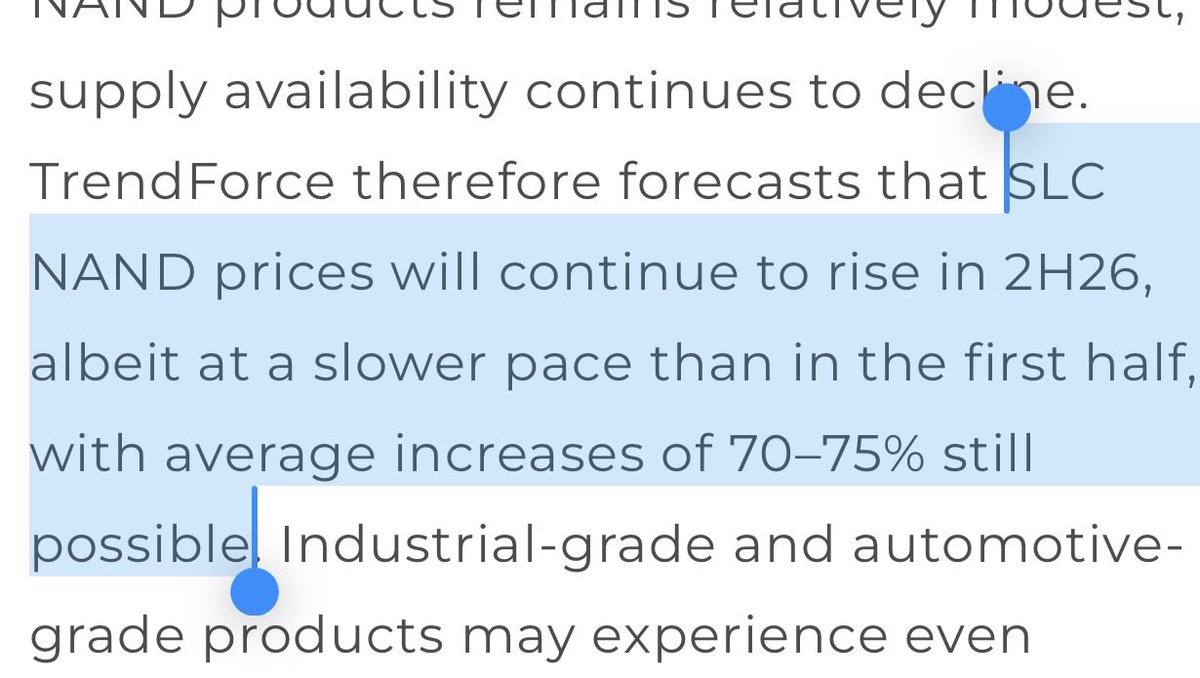
我看到的下一轮“存储”ASP上涨显然是传统存储(DDR2/DDR3/SLC NAND),源于级联瓶颈。这看起来只是存储主题的延伸。
也许MLCC在早期周期方面看起来类似。
如果我们追踪该领域供应链的超级周期影响……
我有信心下一个主题性机会将是进入2027年的光子学。
ENSo on optical vs. photonics... Memory like $MU / $SKHY is in it's current supercycle.
-> RBC channel checks for example projects 80-100% HBM ASP hikes for 2027.
-> Per $NVDA ER, Hyperscaler capex goes up in 2027. Then you have 68% of hyperscaler capex per Trendforce going to DRAM/NAND.
-> 50-70% for next 3-5 years already allocated toward LTAs.
So supercycle is here... demand visibility is high and the price hikes are still ongoing.
As photonics like $SMTC to $AAOI, I expect to cook heavily in 2027 since we're already seeing widespread optical shortages in 2026.
Plus, you're going from $67.7B in 2026 (per GS) to $131.4B TAM in 2027 for optical modules...
Which impacts the DSPs/TIAs/lasers/fiber suppliers before CPO scale up really takes off in 2028.
I don't think we'll ever see the same scale of memory price hikes, but I do think there's a lot room for more for MC growth in optical supply chains (given smaller starting point eg. $1B CW laser supplier vs $1T memory maker).
But still there's room for price hikes on laser content (eg. $15–$20 for 4 70 mW lasers per GS note) since starting point is really cheap... and one component, like cheap InP substrates can break hundreds of billi
阅读 241.0K赞 794转 54评 56引 12藏 269
中文本周我感兴趣的内容速览:
- $INTC CEO 表示部分内存价格已上涨 5-7 倍,并警告短缺将在 2027 年加剧。
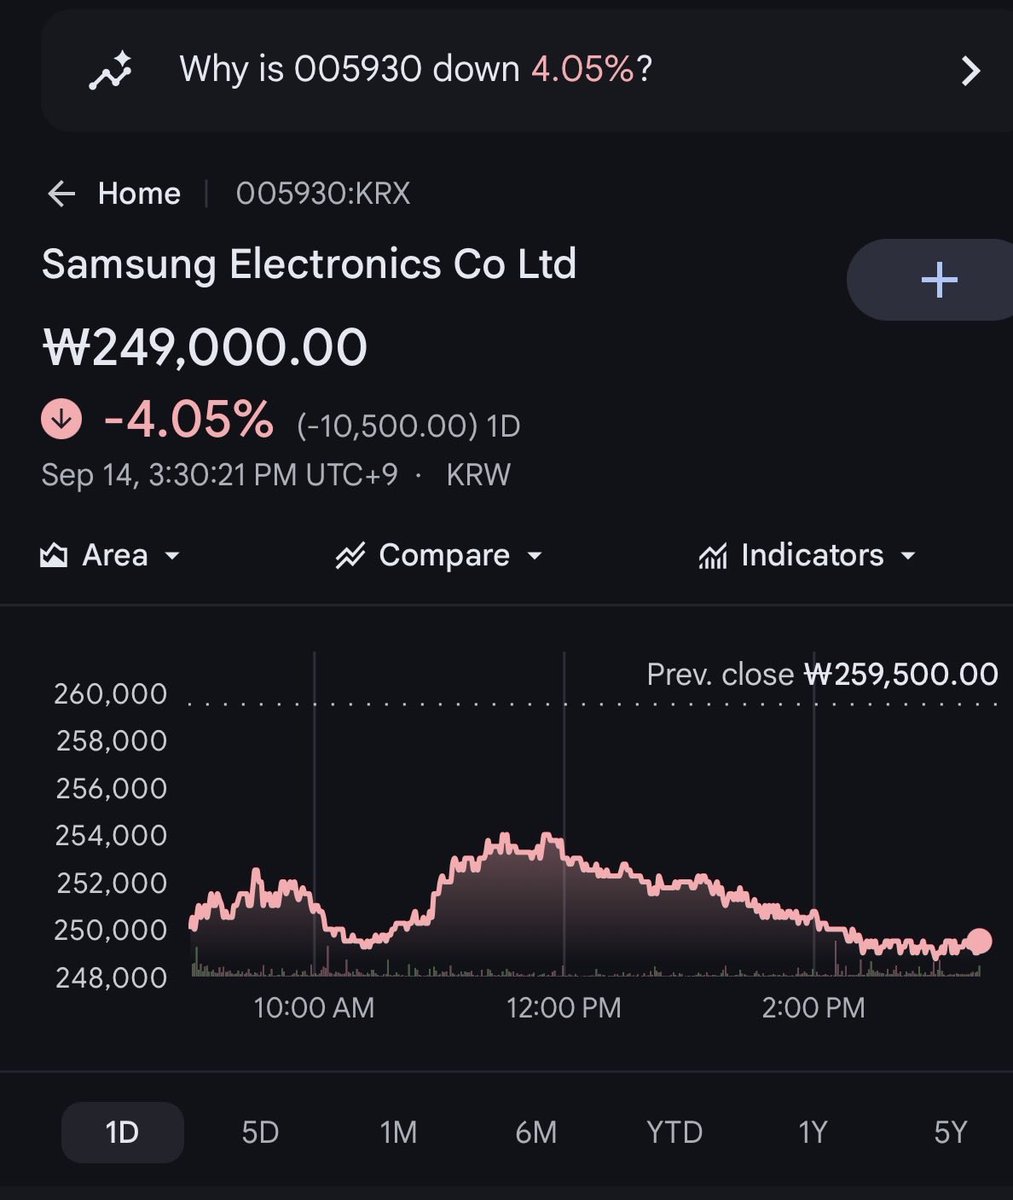
$SNDK / $MU / Samsung 的兄弟们听到这个会很高兴……(来自圣克拉拉 2026 AI Infra Summit)
- $GFS 与 $MRVL 签署扩展 SiGe 产能协议,面向 pluggable/NPO/CPO。“预计将增加大量产能,以支持 Marvell 不断增长的需求。”
我习惯关注 Globalfoundries 相关动态,因为 $SIVE 是他们在 SCALE 上的参考激光器。
- $CIEN 预计到 2029 财年,年收入增长约 30%,调整后毛利率 50%,FCF 利润率 20%。
该公司表示,限制增长的是零部件供应而非需求……从 $NVDA 到上游供应商,供应是收入增长的限制因素,这似乎很普遍。
- 华邦电以 11.2 亿美元收购英飞凌的 NOR Flash 和 F-RAM 业务。
很惊讶英飞凌会出售,因为 NOR Flash 的 ASP 和重要性一直在不断上升,不过这对华邦电的整合有利。
- 据报道,三星扩大 DDR5 模组和 SSD 组装的外包。
我认为一些台湾本地报道指出创见和宇瞻可能是受益者。该报道特别提到了 Dreamtech、Hanyang Digitech 和 SFA Semicon。
我注意到其他韩国公司大约在 1-2 个月前进入新的三星电子合同,可能是传统内存模组……所以认为一些媒体评论可能也错过了这个。也许规模太小,他们没注意到?
- $NBIS 在三个月内第二次上调 AI 云价格(约 17-21%),对其他 Neoclouds(如 $CRWV 到 $IREN 的盈利)是看涨信号。
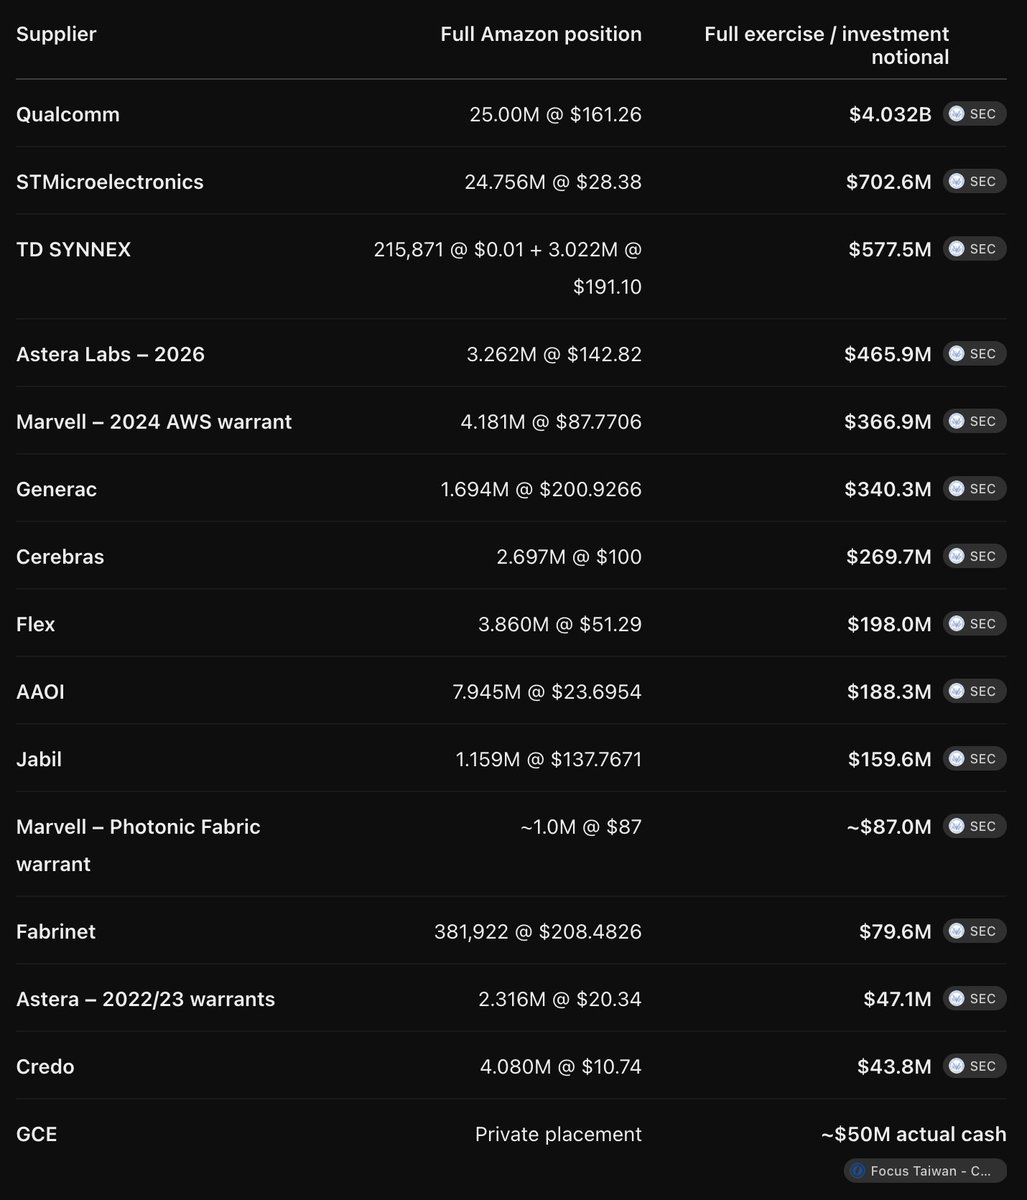
- $AMZN 与 $GNRC 签署 24 亿美元协议,在 2027-2028 年交付发电机……并获得了与最多 80 亿美元总采购额挂钩的认股权证。
值得关注亚马逊与谁签署这些认股权证协议(例如 Alchip、$AAOI、$QCOM、$MRVL 等),以及他们想要什么类型的基础设施采购。
- $TSEM 和 NewPhotonics 开始批量出货激光集成光学引擎。
我不熟悉 NewPhotonics,所以这里不多评论。但今天会做些研究。
- 据报道,高盛认为 ABF 缺口将从 14% 扩大到 51%。预测 2026 下半年短缺 14%,2027 年 34%,2028 年 51%……
更多基板瓶颈问题,需求失衡并不令人意外。
- Crusoe 以 309 亿美元估值融资 39 亿美元。
好吧,这个估值比 Instinct 仅凭 10 万用户就达到 100 亿美元泡沫估值要好……
- 据报道,日本和美国讨论一个 129 亿至 193 亿美元的 $GFS 运营晶圆厂。
这差不多是 Globalfoundries
ENTLDRs of things I found interesting this week:
- $INTC CEO says some memory prices have risen 5-7× and warns the shortage will worsen in 2027.
$SNDK / $MU / Samsung bros will be happy to hear this... (from the AI Infra Summit 2026 in Santa Clara)
- $GFS + $MRVL sign extended SiGe capacity agreement for pluggable/NPO/CPO. "Expected to add significant capacity to support Marvell’s growing requirements."
I like to keep an eye out on Globalfoundries related updates given $SIVE is their reference laser for SCALE.
- $CIEN expects roughly 30% annual revenue growth, 50% adj. gross margin, 20% FCF margin, through FY2029.
The company says component availability, not demand, is limiting growth... Seems common across $NVDA to upstream suppliers that supply is the limiting factor for revenue growth.
- Winbond acquires Infineon's NOR Flash and F-RAM business for $1.12 billion.
Very surprised Infineon sold considering NOR Flash ASP + importance just keep going up and up and up, but good for Winbond consolidation.
- Samsung reportedly expands outsourcing of DDR5-module and SSD assembly.
I think some local Taiwan reports flag Transcend and Apacer as possible beneficiaries. The report specifically i
阅读 224.6K赞 1.2K转 71评 75引 14藏 387